 ResidentialNew
Eevva
Punawale, Chinchwadgaon, Pune
₹83 Lakh
- Property type and configuration
- Apartment · 2 BHK, 3 BHK
- Area
- 801 sq. ft.
Home Loan
Home Loan guidance for the home you want to own
Buying a new flat, a resale home or building your own house? FinanceGuru helps you understand eligibility, compare participating lenders and move from enquiry to disbursement with one advisor.
Why FinanceGuru
Finance a new home, resale property or construction requirement with guided lender selection.
Review options from participating banks and housing finance companies instead of approaching each one separately.
Shortlist a home through Property Advisory and plan its financing with the same team.
Use the property pre-assessment and EMI calculator to see what a purchase could mean for your monthly budget.
Know which income, KYC and property papers a lender is likely to ask for before you apply.
Salaried, self-employed and joint applicants are assessed differently. We explain what applies to you.
Your advisor stays with the case through sanction, legal and technical checks and disbursement.
Eligibility
Every lender applies its own criteria. These are the factors most lenders review.
Get an indicative view of what you may be eligible for before you apply. The result is indicative; the lender makes the final assessment.
Compare lenders
Government banks, private banks and NBFCs / housing finance companies, each from the lender's current published policy for this loan.
Planning tools
Get an indicative loan amount against a property, then see what the monthly instalment could look like.
Home loan planning
Get an indicative assessment of the maximum loan amount based on the property value and transaction type.
No personal or contact details are required.
An estimated planning tool—not a lender offer.
Monthly EMI
₹24,168
Total Interest
₹28,00,271
Total Repayment
₹58,00,271
StartYear 20
Property Advisory
Browse residential properties listed with FinanceGuru and plan the Home Loan alongside your shortlist.
Prepare ahead
Having these ready helps your advisor assess your case accurately. The final list depends on the lender and your profile.
Rates differ by lender and depend on your credit history, loan amount, income profile, the security offered and market conditions. Your advisor will share the options currently open to you.
Possible costs include processing and documentation fees, legal and valuation charges, stamp duty, and prepayment or foreclosure charges where applicable. Ask for the full schedule of charges before you accept an offer.
How it works
The usual steps from enquiry to disbursement. Each lender follows its own assessment and timelines.
Share the property you plan to buy and a few basic details.
An advisor reviews income, obligations, credit position and the property budget with you.
We help you collect personal, income and property documents and log in the application with your consent.
The lender assesses your profile and carries out legal and technical checks on the property.
If approved, the lender issues a sanction letter with its terms.
Loan documents are signed and the lender disburses as per its terms and the purchase stage.
Answers before you apply
The amount depends on your income, age, existing EMIs, credit history and the lender's assessment of the property. Lenders finance only a part of the property value, so plan for your own contribution as well. The tools on this page give an indicative view; the final amount is decided by the lender.
Yes. Many buyers check eligibility first so they know a comfortable budget. Some lenders also issue an in-principle sanction that is valid for a limited period, subject to their terms and to the property meeting their norms.
Yes. Adding an earning co-applicant such as a spouse or parent may improve eligibility because lenders can consider the combined income. Co-owners of the property are generally required to be co-applicants.
A floating rate moves with the lender's benchmark, so your EMI or tenure can change over time. A fixed rate stays the same for the agreed period. Availability and terms differ by lender, and your advisor can explain the options open to you.
Lenders usually review the sale agreement, title documents, approved plans and relevant approvals, and carry out their own legal and technical verification. The exact list depends on the property and the lender.
Yes. Through Property Advisory you can browse listed residential properties, enquire about one and discuss its financing with the same team.
Related products
Talk to FinanceGuru
Apply online, or speak to an advisor who can review your profile and explain suitable options. No application is submitted to a lender without your consent.
FinanceGuru is a loan and property advisory brand owned by Real Money and is not a lender. Loan approval, amount, interest rate, tenure, charges and timelines are decided by the concerned financial institution after its own eligibility assessment. Calculator results are indicative only.
Property Advisory
Browse residential properties listed with FinanceGuru and plan the Home Loan alongside your shortlist.
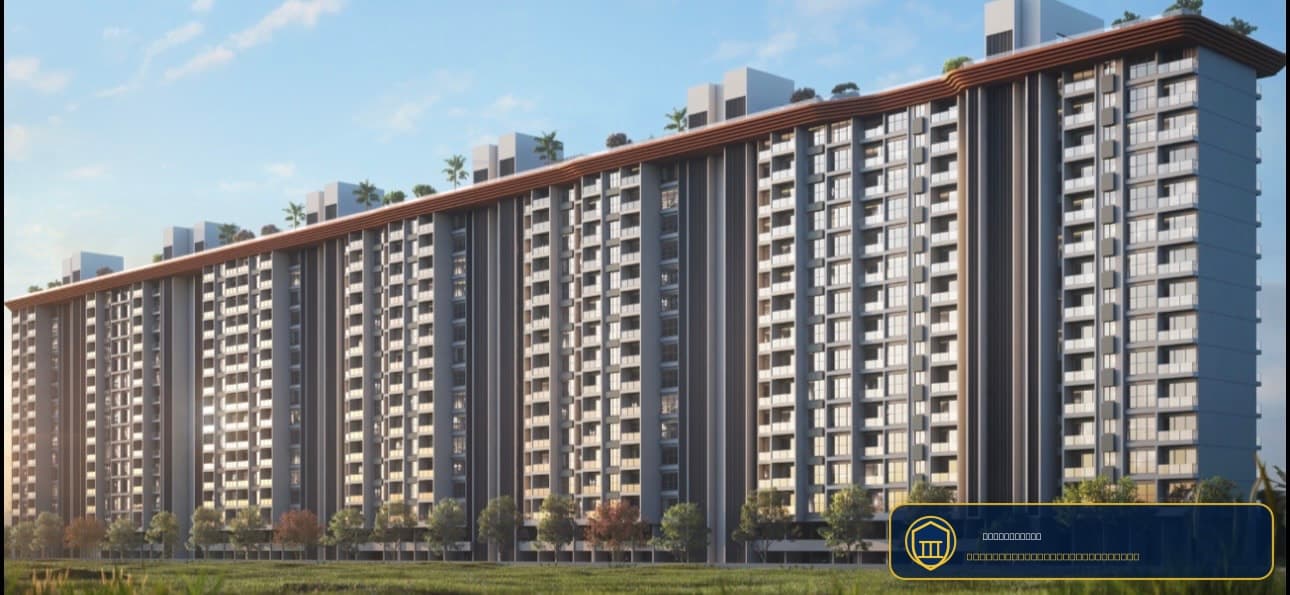
ResidentialNewPunawale, Chinchwadgaon, Pune
₹83 Lakh
 ResidentialNew
Infotech Park (Hinjawadi), Pune
₹95.5 Lakh
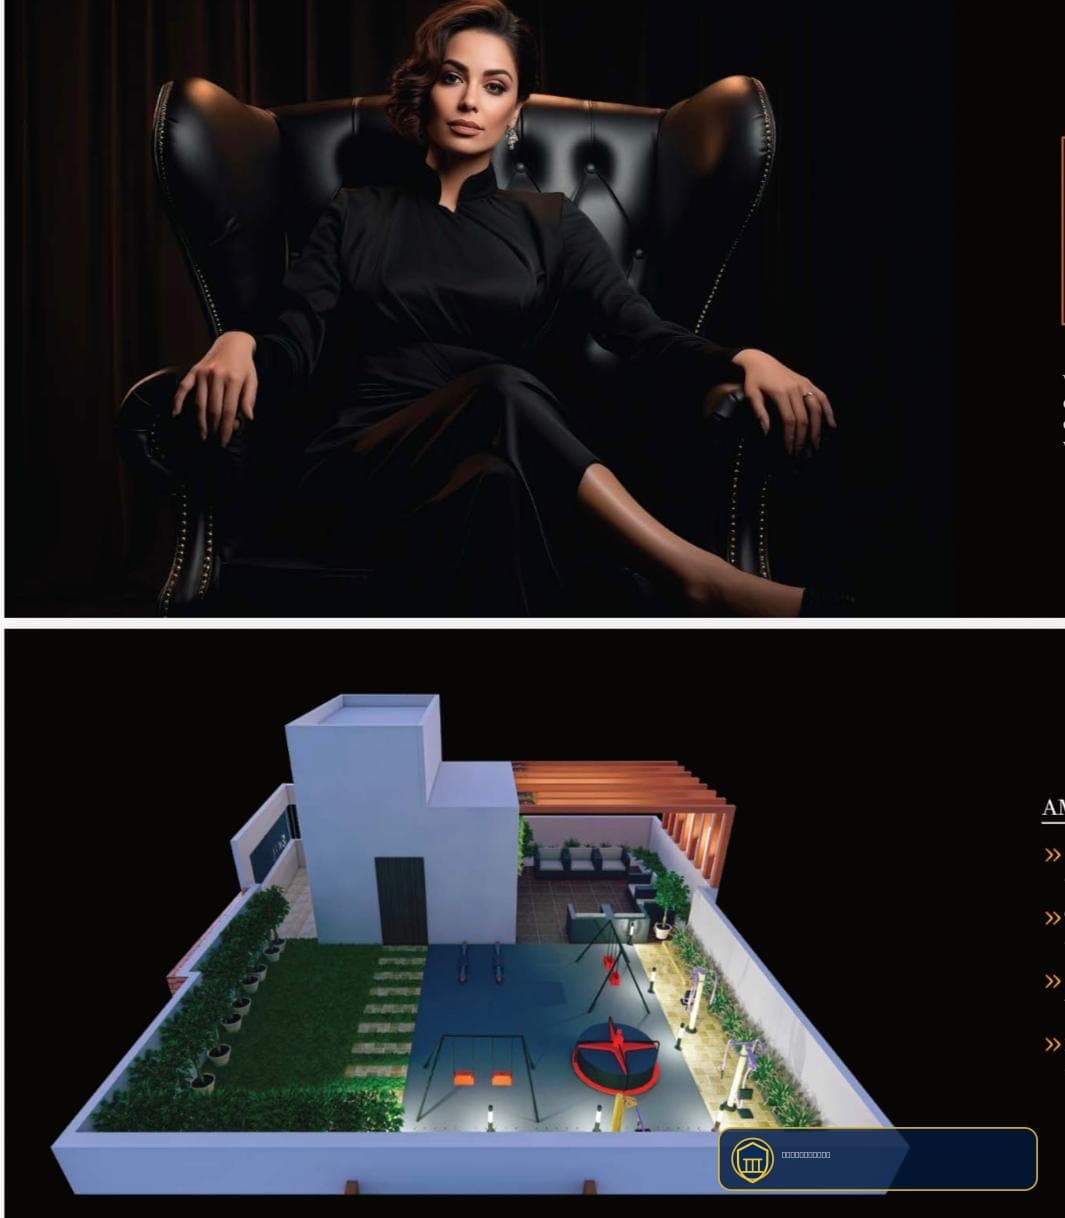 ResidentialNew
Samarth Colony, Baner, Pune
₹1.8 Crore
 ResidentialNew
Nanded city, Pune
₹85.0 Lakh
 ResidentialNew
Wakad, Pune
₹1.06 Crore
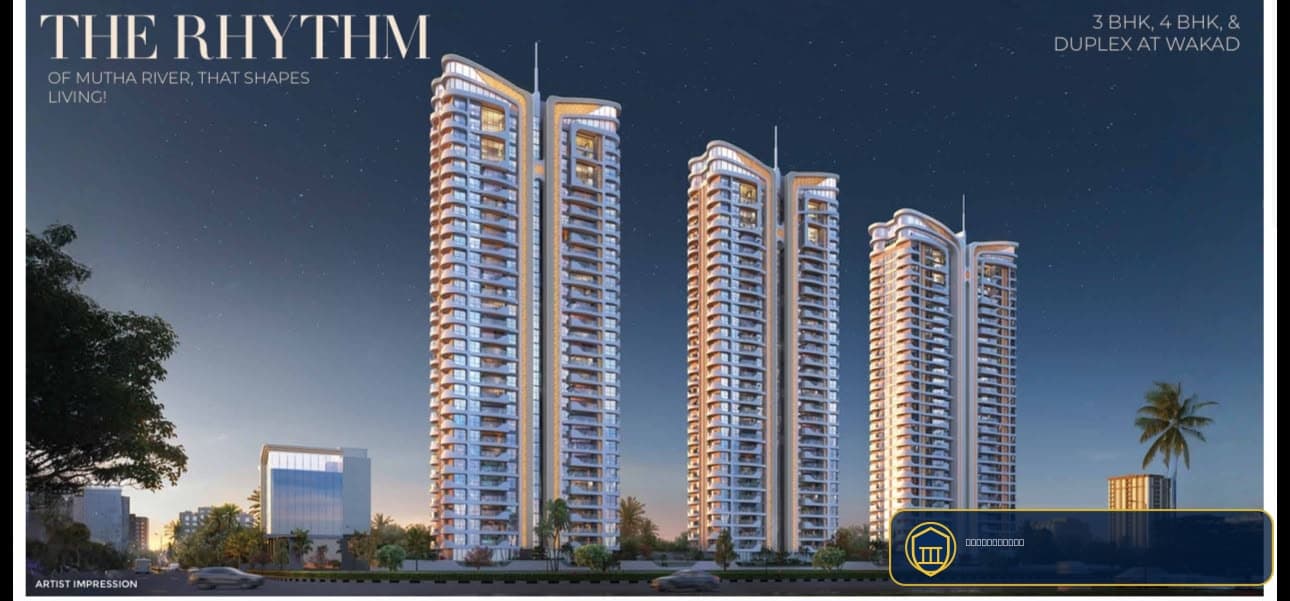 ResidentialNew
Kaspate wasti wakad, Pune
₹1.99 Crore
Listings are shown as published by FinanceGuru Property Advisory. Availability and price are subject to confirmation; loan eligibility for any property is assessed separately by the lender.